
Introduction
By Ahmad, Editor, thoughtsinenglish.org | Published: October 13, 2026 | Last updated: October 13, 2026
Hair salon insurance quotes tell you what it costs to protect your chairs, clients, and staff. This guide is for salon owners, independent stylists, and booth renters who want real numbers, plain-English coverage explanations, and a clear way to compare offers.
Hair salon insurance quotes typically land near $35 a month for general liability and about $70 for a business owner’s policy, according to Insureon’s published medians. Your price shifts with location, staff, and coverage limits, so compare at least three quotes. It is written for salon owners and stylists.
Table of Contents
- What Are Hair Salon Insurance Quotes?
- Which Insurance Policies Does a Hair Salon Need?
- How Much Do Hair Salon Insurance Quotes Cost?
- Is Business Insurance Expensive for a Hair Salon?
- What Affects Your Hair Salon Insurance Quote?
- How Do You Compare Commercial Insurance Carriers and Online Quotes?
- Does a Limited Company Salon Need Different Insurance?
- When to Get Hair Salon Insurance Quotes
- How to Choose the Right Hair Salon Insurance Quote
- Smart Tips to Lower Your Premium
- Common Mistakes to Avoid
- Frequently Asked Questions
- Conclusion
What Are Hair Salon Insurance Quotes?
Short answer: A hair salon insurance quote is a written estimate showing the premium, coverage limits, and deductible an insurer would charge to protect a salon business. It becomes a policy only after you accept it and pay.
Think of a quote as a price tag with the fine print attached. It lists what is covered, what is excluded, and what you would pay monthly or yearly. A commercial insurance online quote is the same estimate delivered through a web form instead of a phone call, often within minutes.
Quotes are not all alike. One may offer a $1 million per-occurrence limit with a $500 deductible, while another offers half that for less money. That is why the lowest number on the page is rarely the best fit for your salon.
Which Insurance Policies Does a Hair Salon Need?
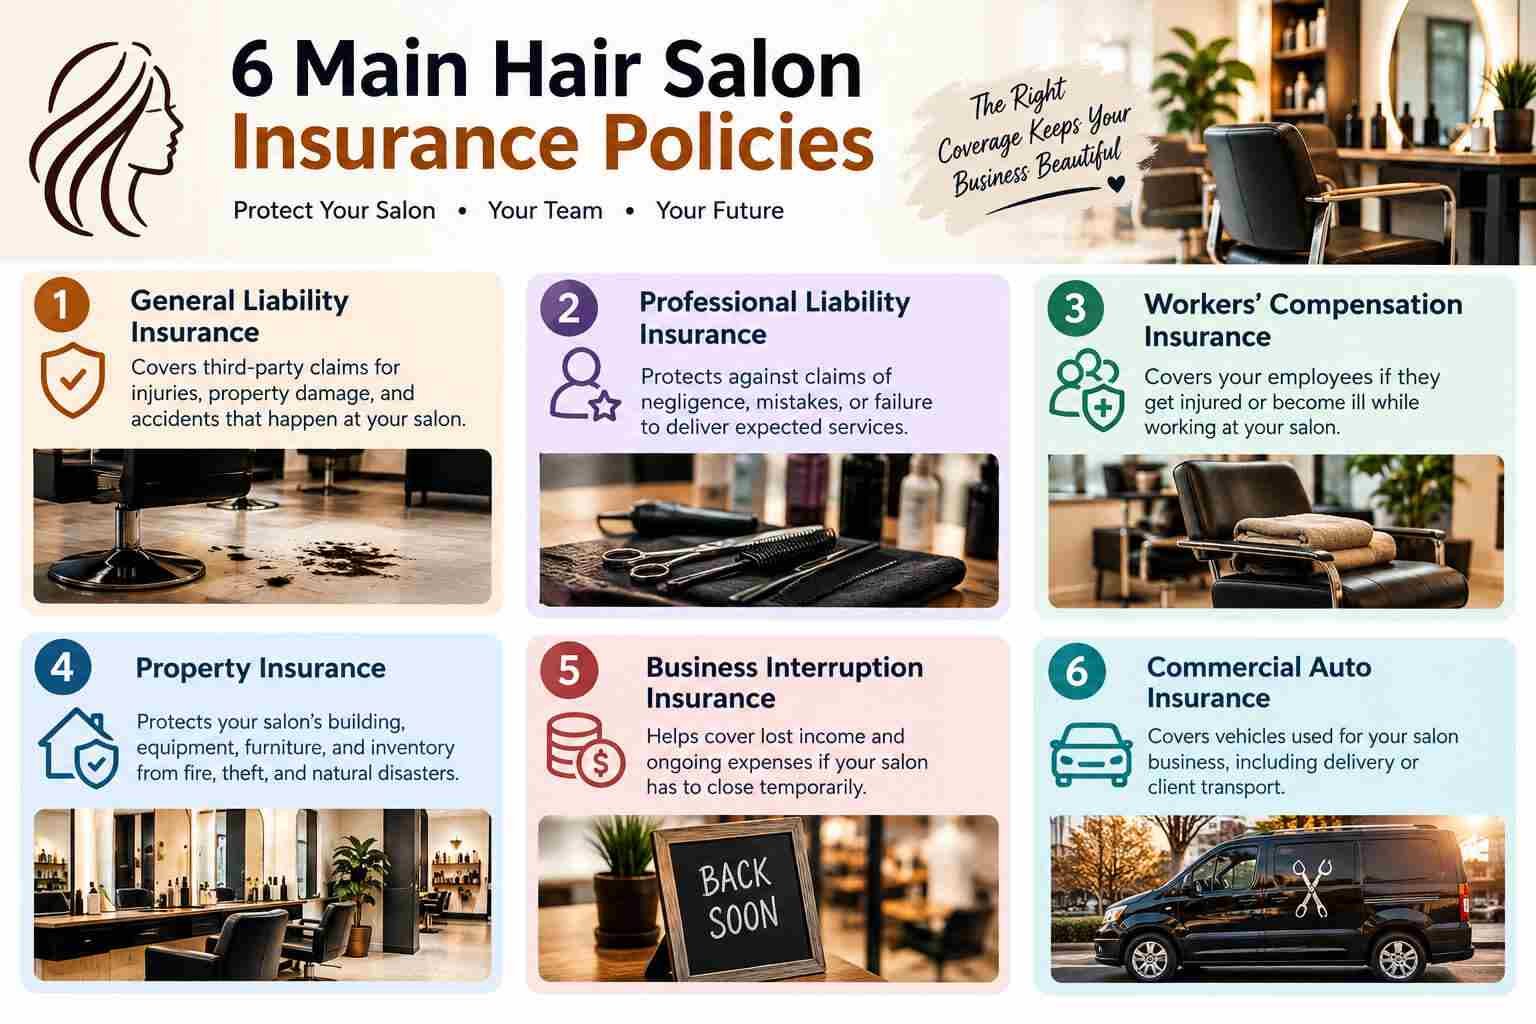
In short, most salons need liability cover, property cover, and workers’ compensation once they hire staff. Booth renters and independent stylists still need their own protection.
According to the U.S. Small Business Administration, a sound rule is to insure against anything you could not afford to pay for on your own. For a salon, that could mean a client’s reaction to a treatment, a slip near the shampoo bowls, a burst pipe, or stolen tools.
NerdWallet’s salon guide adds two useful points. Stylists who simply rent a booth still need their own business insurance, and salons that use independent contractors may still need workers’ compensation.
General Liability Insurance
General liability is the foundation. According to Insureon, it helps pay legal costs when a client claims bodily injury, damage to their property, or advertising injury, and it often includes product liability. Spilled dye on a client’s coat is the classic example.
Insureon’s typical hair salon policy carries a $1 million per-occurrence limit, a $2 million aggregate limit, and a $500 deductible. Use those numbers as a baseline when you compare offers.
Professional Liability Insurance
Professional liability, also called errors and omissions cover, responds when a client says your work fell short. Think of a colour that came out the wrong shade or a cut that did not match what was agreed.
Some insurers describe this as a professional insurance policy, so read the wording on each quote. Where general liability handles accidents, this cover handles complaints about the service itself.
Business Owner’s Policy (BOP)
A BOP bundles general liability with commercial property cover, and NerdWallet’s BOP explainer notes that business interruption is part of the standard package too. Insureon says a BOP usually costs less than buying each piece separately.
It also reports that its agents recommend a BOP most often for small salons, because it protects equipment, stock, and furnishings alongside liability.
Workers’ Compensation Insurance
If you employ staff, workers’ compensation pays medical bills and partial wages when someone is hurt on the job. Rules differ by state, so check your own state’s requirements before you open.
Insureon also recommends it for sole proprietors, because health plans can deny claims for injuries that are work-related.
Cyber and Commercial Auto Insurance
Salons that store client contact details or take card payments may want cyber insurance, which helps cover breach-related costs. Mobile hairdressers who drive a business-owned vehicle need commercial auto.
Personal or rented vehicles used for work usually fall under hired and non-owned auto cover instead.
How Much Do Hair Salon Insurance Quotes Cost?
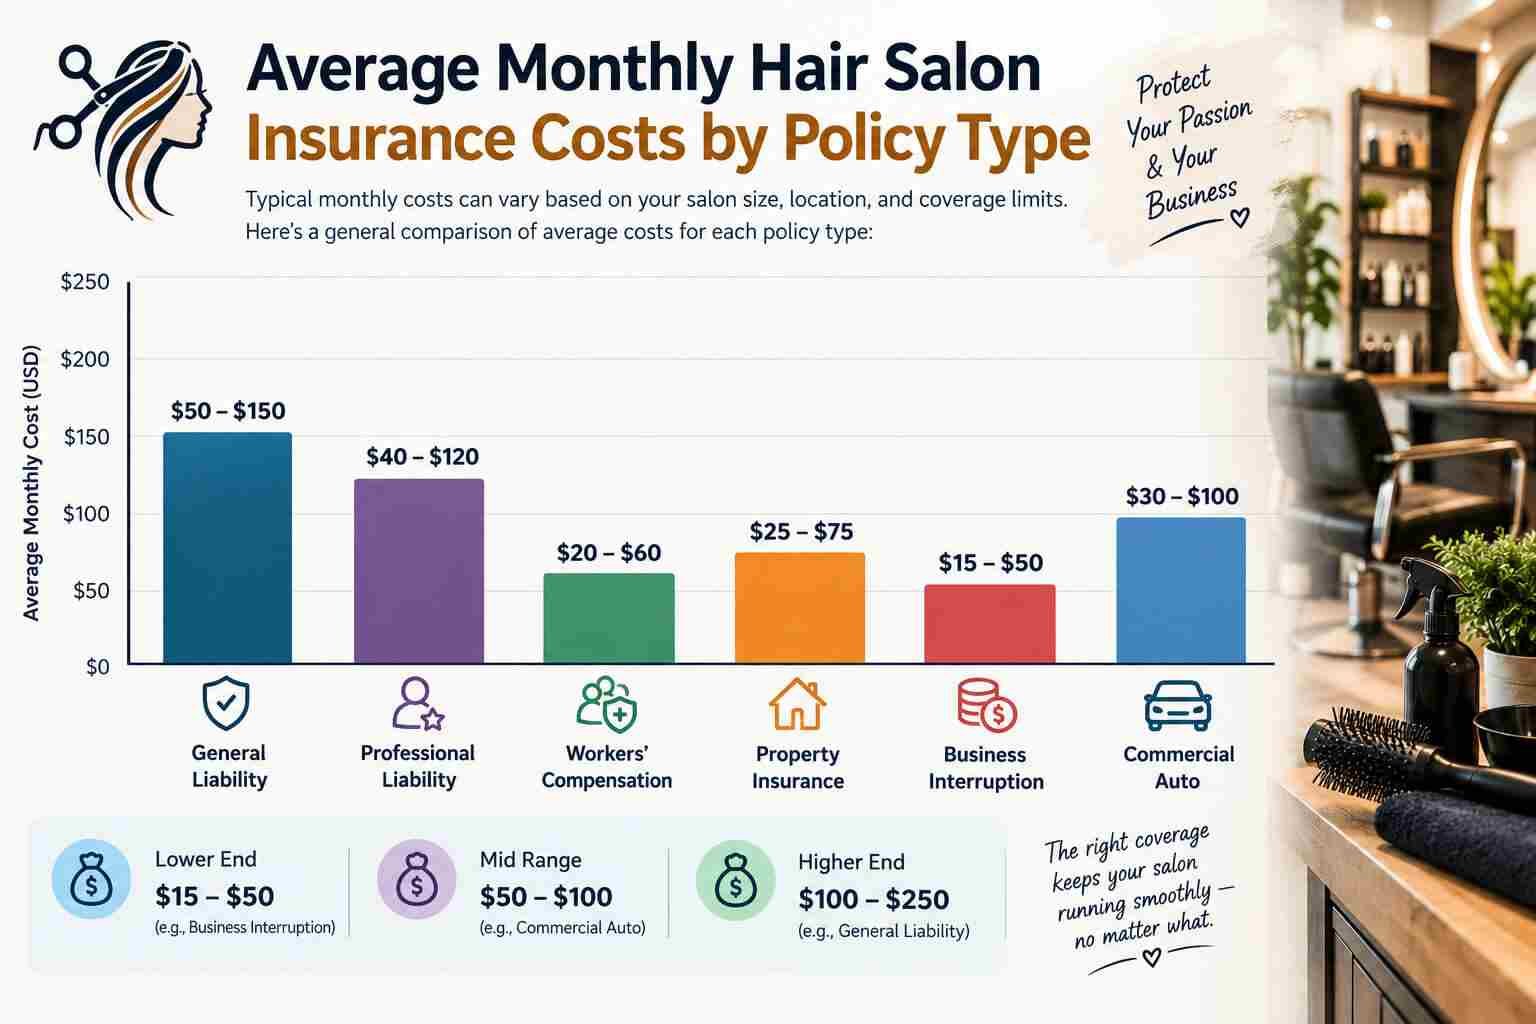
In short, Insureon’s published medians for hair salons run from about $35 a month for general liability to about $245 for commercial auto. A core bundle of a BOP plus workers’ compensation works out to roughly $133 a month on those figures.
According to Insureon’s hair salon cost page, these numbers are medians of policies bought by its hair salon customers, which keeps unusually high or low premiums from skewing the picture. We reviewed the page on October 13, 2026.
| Policy | What it covers | Typical cost per month | Typical cost per year | Best for |
|---|---|---|---|---|
| General liability | Client injury, property damage, advertising injury | $35 | $420 | Every salon and stylist |
| Business owner’s policy | General liability plus property | $70 | $841 | Salons with equipment and stock |
| Professional liability | Claims over poor results or errors | $42 | $500 | Colour, chemical, and cutting services |
| Workers’ compensation | Employee injuries and lost wages | $63 | $757 | Salons with employees |
| Cyber insurance | Data breach response costs | $129 | $1,552 | Salons storing client data |
| Commercial auto | Business-owned vehicles | $245 | $2,942 | Mobile salons |
Source: Insureon, hair salon insurance cost page, reviewed October 13, 2026.
A Simple Worked Example
Illustrative example, not a real client: a two-chair salon with one employee buys a BOP at $841 a year and workers’ compensation at $757 a year. That totals $1,598 a year, or about $133 a month.
Adding professional liability at $500 brings the total to $2,098 a year, roughly $175 a month.
Why Different Websites Show Different Averages
While preparing this guide at Thoughts in English, we compared cost pages from three providers and found general liability for salons quoted anywhere from about $19 to $112 a month. The gap comes from method, not mistakes.
NEXT Insurance reports that 63% of its hair stylist customers pay about $19 a month for general liability. Research by MoneyGeek shows standardized quotes ranging from $42 a month in West Virginia to $112 in California.
Insureon’s $35 sits between them. Treat every average as a starting range, then let your own quote settle the number.
Is Business Insurance Expensive for a Hair Salon?
In short, it is usually modest next to the cost of one uninsured claim, but it grows quickly as you add staff, vehicles, and extras.
Break the medians down by day. General liability at $420 a year is about $1.15 a day, and a BOP at $841 a year is about $2.30 a day. Compare that with a legal defence bill or replacing stolen equipment, and the premium looks different.
Costs climb when you add workers’ compensation, cyber, or commercial auto. That is why the best rates for business insurance come from matching cover to real risks instead of buying every extra on the menu.
Running a salon takes nerve, and our small business motivation quotes are there for the days it feels heavy.
Three habits help most. Bundle into a BOP where you qualify, classify your staff correctly for workers’ compensation, and compare several carriers before you decide.
What Affects Your Hair Salon Insurance Quote?
In short, your quote depends on what you do, where you do it, and how much protection you choose. According to Insureon, premiums reflect the services you offer, your equipment and property value, annual revenue, location, headcount, and your limits and deductibles. Here is how each piece plays out.
Location and Property Value
Where you operate matters. MoneyGeek’s data shows workers’ compensation for hair salons at about $13 per employee per month in Indiana versus $29 in California. Local weather risk, construction costs, and property values also feed into the price.
Staff Size and Roles
An independent stylist pays less than a salon with several employees, according to Insureon. More staff means more payroll for workers’ compensation, more people handling client data, and more chances of a claim.
Services and Products
Colour, relaxers, keratin treatments, and extensions carry different risks from a basic cut. Be upfront about every service you offer. A quote built on an incomplete list can cause problems when you try to claim.
Claims History, Limits, and Deductibles
A clean record helps. So does a higher deductible, as long as you could comfortably pay it. Higher limits raise the premium but protect more of your savings.
Keep limits identical when you compare. Otherwise you are not comparing quotes at all.
How Do You Compare Commercial Insurance Carriers and Online Quotes?
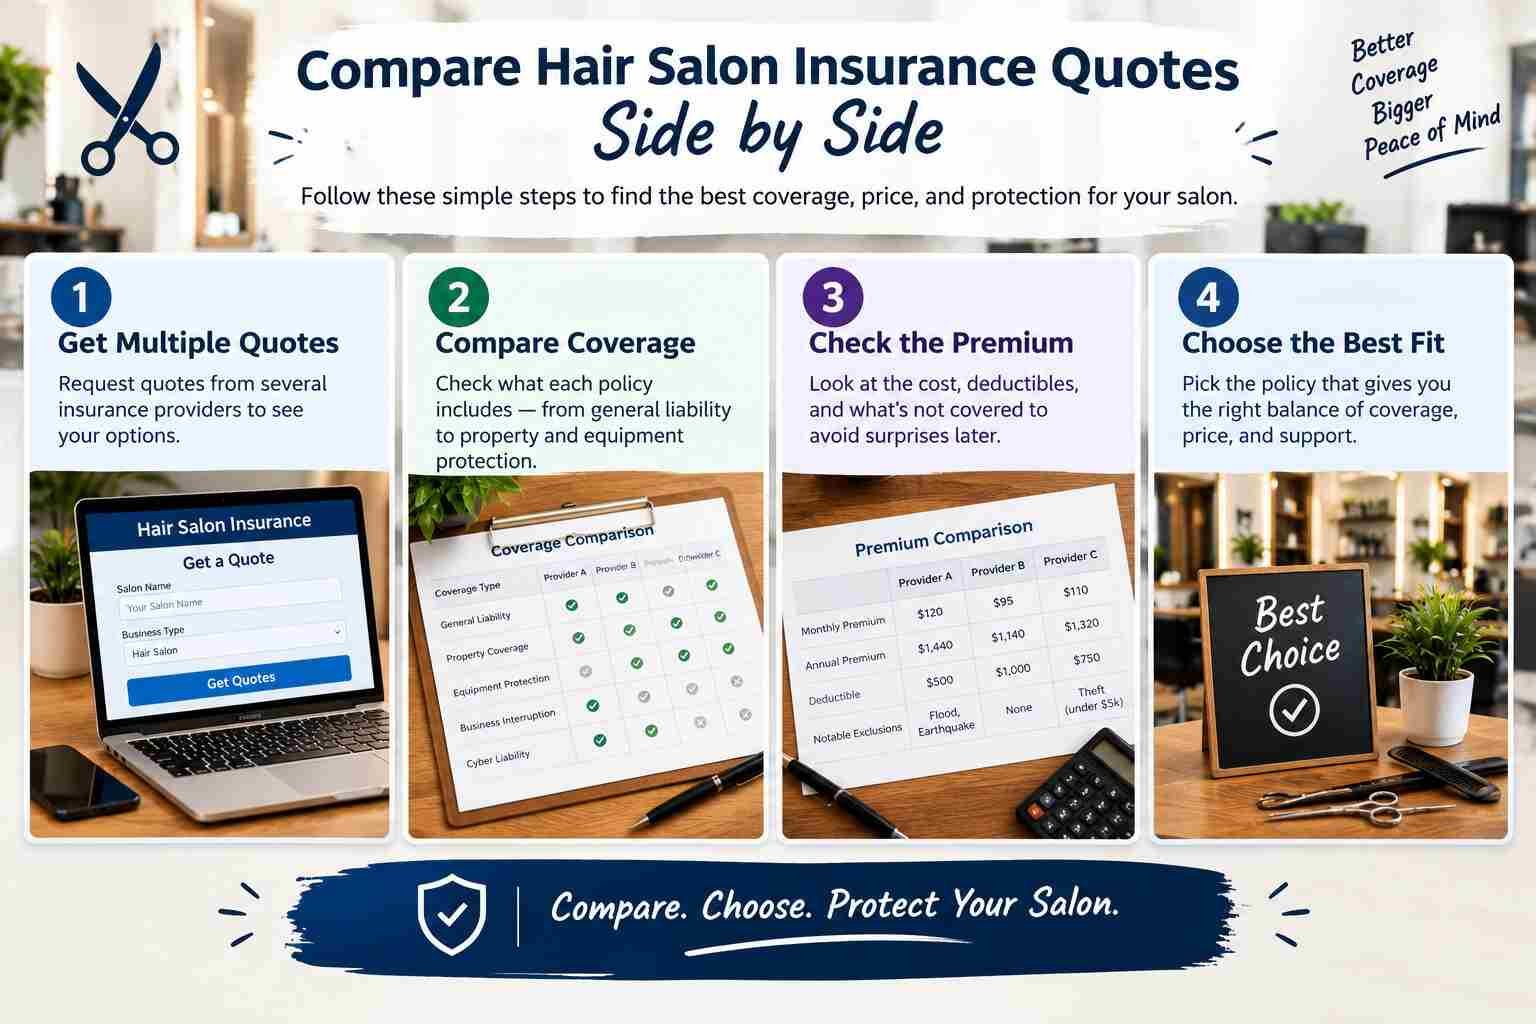
In short, request at least three quotes with identical limits and deductibles, then compare price, exclusions, and claims support. Finding the best hair salon insurance quotes is a matching exercise, not a price hunt.
The U.S. Small Business Administration lists four steps: assess your risks, find a reputable licensed agent, shop around, and re-assess every year. It also notes that agents earn commissions, so look for one who listens to your needs.
Online Quote or Licensed Agent?
An online form is fast and works well for simple, low-risk salons. A licensed agent can shop several insurers and explain exclusions. Insureon says proof of insurance typically arrives within 24 hours of applying.
Using both works well: an online quote for a baseline, then an agent to fine-tune it.
What to Look for in Commercial Insurance Carriers
NerdWallet rates small-business insurers on financial strength, complaint records, digital tools, and customer service availability. Borrow that checklist.
Ask how claims are filed, how quickly adjusters respond, and whether the carrier regularly insures salons.
Do Business Insurance Calculators Help?
A business insurance calculator gives a ballpark, which is handy for budgeting. MoneyGeek, for example, offers a hair salon cost calculator.
It cannot see your claims history, staffing, or services, so treat the result as a range and confirm it with a real quote.
Does a Limited Company Salon Need Different Insurance?
In short, the core policies are the same, but a limited company must still insure the business itself and any staff. Company status does not replace insurance.
A limited company is the UK term for what is usually an LLC or corporation in the US. According to the U.S. Small Business Administration, those structures can protect personal property from lawsuits, but only up to a point. Insurance fills the gaps.
Rules for employee cover differ by country. In the UK, employers’ liability insurance is generally required once you hire staff. Check current rules with your local authority and a licensed broker before you open.
Most prices in this guide are US figures, so UK owners should treat them as a rough comparison and request local quotes.
When to Get Hair Salon Insurance Quotes
Timing matters as much as price. Request quotes in these situations:
- Before you sign a salon lease, since landlords commonly ask for proof of cover.
- Before you hire your first employee, so workers’ compensation is in place from day one.
- Before you rent a booth or chair, because you will need your own policy.
- When you add services such as chemical treatments, extensions, or mobile appointments.
- After buying new equipment or renovating, since your property values have changed.
- Each year at renewal, in line with the SBA’s advice to re-assess annually.
- Whenever a client, landlord, or supplier asks for a certificate of insurance.
Opening soon? Announce it with grand opening captions for Instagram once your cover is in place.
How to Choose the Right Hair Salon Insurance Quote
Follow these steps in order. They keep the process calm and the comparison fair.
- List your risks. Walk through the salon and note what could injure a client, damage property, or interrupt business.
- Confirm what the law requires. Visit your state’s official website to check workers’ compensation and other rules.
- Gather your details. Have revenue, payroll, equipment value, services, and claims history ready.
- Request at least three quotes with the same limits. Insureon’s typical policy, $1 million per occurrence, $2 million aggregate, and a $500 deductible, is a sensible baseline.
- Read the exclusions. Check chemical services, product claims, mobile work, and independent contractors.
- Compare total yearly cost and claims support. The cheapest offer is not always the best value.
- Decide, then set a reminder. Schedule next year’s review the day you buy.
Use this table as a starting point for the conversation with your agent. It is a guide, not a recommendation.
| Your setup | Sensible starting cover | Consider adding |
|---|---|---|
| Booth renter or solo stylist | General liability and professional liability | Cyber if you take cards or store client data |
| Owner with chairs but no staff | BOP and professional liability | Cyber for booking and payment data |
| Salon with employees | BOP, professional liability, and workers’ compensation | Cyber, plus commercial auto if you own a vehicle |
| Mobile hairdresser | General liability and professional liability | Commercial auto, or hired and non-owned auto |
Smart Tips to Lower Your Premium
You cannot haggle a premium to zero, but these habits can keep it fair:
- Bundle where you can. A BOP often costs less than separate policies.
- Classify staff correctly. Insureon notes that accurate workers’ compensation class codes help control cost.
- Show your safety routines. Ask your agent whether documented steps, such as patch tests for dye and written consent for chemical services, can help.
- Pick a deductible you can afford. A higher deductible lowers the premium, but only if you can pay it.
- Keep good records. Store receipts, equipment lists with photos, and client consent forms in one place.
- Ask about discounts and payment plans. Insurers differ, and it costs nothing to ask.
- Review every year. Your salon changes, and your cover should change with it.
A confident brand helps too. Browse our hairstylist quotes for ideas you can use in your salon bio.
Common Mistakes to Avoid
Most costly errors are simple ones. Watch for these:
- Choosing on price alone. A low premium with narrow limits can leave you exposed.
- Assuming someone else’s policy covers you. Booth renters need their own protection.
- Skipping workers’ compensation. Missing required cover can lead to fines and penalties.
- Comparing mismatched limits. Different limits and deductibles make two quotes impossible to judge fairly.
- Hiding or forgetting services. Tell the insurer about every treatment you offer.
- Never updating after growth. New staff, equipment, or a second location change your risk.
- Treating a calculator as a quote. Calculators estimate; only a quote reflects your details.
Taking risks in business is normal, but taking unmanaged ones is not. Our entrepreneur quotes about risk put that balance into words.
Frequently Asked Questions
How much does hair salon insurance cost per month?
Insureon’s published medians for hair salons are about $35 a month for general liability, $70 for a business owner’s policy, $42 for professional liability, and $63 for workers’ compensation. Your quote will differ based on location, staff, services, limits, and deductible, so request several quotes before deciding.
Do I need my own insurance if I rent a booth?
Yes, in most cases. NerdWallet notes that stylists who simply rent a booth still need their own business insurance. Start with general and professional liability, then ask a licensed agent whether your state or your booth agreement requires anything more.
What is the difference between general and professional liability for a salon?
General liability covers accidents, such as a client slipping or dye staining their clothes. Professional liability covers complaints about your work, such as a wrong colour or an unwanted cut. Many salons carry both because the two policies respond to different kinds of claims.
Is a business owner’s policy enough for a hair salon?
Often it is a strong start. A BOP bundles general liability with commercial property cover, and Insureon says it is the policy its agents recommend most often. It does not replace workers’ compensation, professional liability, cyber, or commercial auto, so add those if you have staff, store client data, or drive for work.
How fast can I get proof of insurance?
Insureon says you can typically get proof of insurance within 24 hours of submitting an application. Timing varies by insurer and by how complete your information is. Have your revenue, payroll, equipment value, and list of services ready, and ask for a certificate of insurance if your landlord requires one.
Can a business insurance calculator replace a real quote?
No. A calculator gives a rough range for budgeting, but it cannot see your claims history, staffing, services, or exact limits. Use it to set expectations, then request actual hair salon insurance quotes with matching limits and deductibles, and compare them side by side before you commit.
Conclusion
Hair salon insurance quotes are easier to judge once you know the building blocks: liability, property, workers’ compensation, and a few optional extras. Use real figures as a range, compare quotes with identical limits, and revisit your cover every year as your salon grows.
Best for: new salon owners, booth renters, and growing salon teams who want clear numbers before they commit.
Ready for more? Explore our related guides, such as self-employed quotes, women entrepreneur quotes, and beauty salon captions, here at Thoughts in English.
Sources: Insureon (hair salon insurance cost); U.S. Small Business Administration (Get business insurance); NerdWallet (beauty salon insurance and business owner’s policy); MoneyGeek (hair salon insurance cost); NEXT Insurance (hair stylist insurance cost).
About the author: Ahmad is the founder of Thoughts in English, where he writes about poetry, quotes, and everyday emotions. This guide was researched from published insurer cost pages and SBA guidance.